How to Choose Credit Help in Philadelphia Without Wasting Time or Money
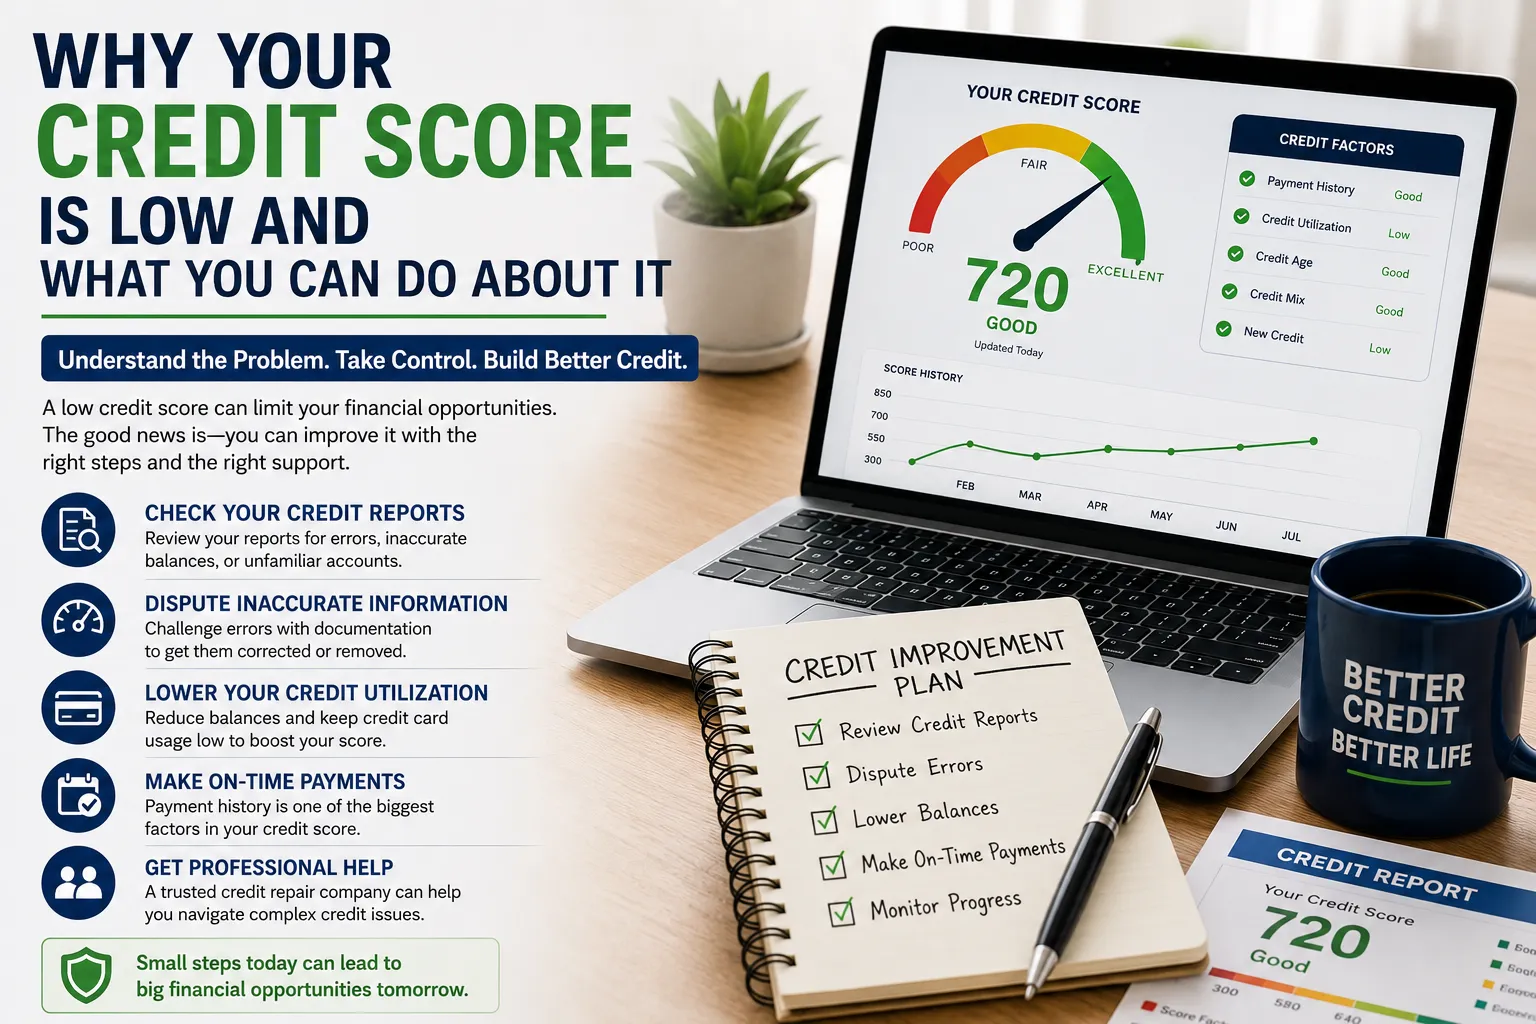
When your credit report contains collection accounts, late payments, high balances, or information you do not recognize, knowing where to begin can be difficult. A search for credit repair companies may produce many options, but not every provider offers the same services or approach.
The right starting point is not simply finding a company that promises fast results. It is understanding your credit problem, knowing which issues can actually be addressed, and choosing assistance that gives you clear information about the process.
Whether you are considering professional help or planning to work on your credit independently, learning the basics can help you avoid unnecessary costs and unrealistic expectations.
Identify Your Credit Problems Before Choosing a Service
Before contacting a credit professional, review your credit reports.
Look beyond the score and examine the accounts contributing to your overall credit profile.
Pay particular attention to:
- Late or missed payments
- Collection accounts
- Charge-offs
- High revolving balances
- Accounts you do not recognize
- Incorrect balances
- Duplicate accounts
- Incorrect account status
- Inaccurate personal information
- Hard inquiries you do not recognize
Create a simple list of the problems you find. Separate information that appears inaccurate from negative information that appears legitimate.
This step matters because different problems require different solutions. A reporting error may require a dispute, while a legitimate credit card balance may require budgeting and debt repayment.
What Does a Credit Repair Consultant Actually Do?
A credit repair consultant can help consumers understand information appearing on their credit reports and organize a plan for addressing potential problems.
Depending on the provider, assistance may include reviewing credit reports, identifying potentially inaccurate information, helping organize supporting documents, explaining dispute procedures, and discussing credit-management habits.
A consultant should not be viewed as someone who can instantly erase negative credit history.
If information is accurate and legally reportable, simply hiring a professional does not automatically make it disappear. The purpose of professional guidance should be to help you understand your options and take appropriate steps.
Consumers should remain involved throughout the process and understand what actions are being taken.
Learn the Difference Between an Error and a Negative Account
This is one of the most important concepts in credit repair.
A negative account can be unpleasant, but that does not automatically mean it is inaccurate.
For example, a legitimately missed payment may negatively affect your credit history. If the creditor is reporting the payment accurately, disputing it simply because you dislike the entry is not the same as correcting a reporting error.
An error could involve information such as:
- A payment incorrectly reported as late
- A balance that does not match account records
- A debt that belongs to someone else
- The same account appearing more than once
- Incorrect account dates
- An account incorrectly shown as open or closed
If you believe something is inaccurate, collect documentation supporting your position before submitting a dispute.
Documentation Makes Credit Problems Easier to Manage
Credit repair can become confusing when you have several accounts and years of financial records.
Create a folder—digital or physical—for important documents.
You might organize it into categories such as:
Credit reports: Keep copies of relevant reports and note the date you obtained them.
Account statements: Save statements showing balances, payments, and account activity.
Correspondence: Keep letters, emails, and other communications with creditors or reporting agencies.
Dispute records: Record what information you challenged, when you submitted the dispute, and what response you received.
Good organization can make it easier to track progress and identify unresolved issues.
How to Evaluate Credit Repair Companies
If you are comparing credit repair companies, ask specific questions before signing up.
Find out:
- What services does the company provide?
- How does the company identify potentially inaccurate information?
- What documentation will you need to provide?
- What fees will you pay?
- What responsibilities remain with you?
- How are disputes handled?
- What results can the company realistically promise?
Be cautious when a provider guarantees a specific credit-score increase or promises that all negative accounts will be removed.
Credit histories are individual. A strategy that works for one person may not produce the same outcome for another.
A transparent provider should explain the process clearly rather than relying on dramatic promises.
Philadelphia Consumers Should Consider Their Specific Financial Goals
Searching for credit repair Philadelphia services may be the first step, but your reason for improving your credit should guide the broader strategy.
Perhaps you are preparing for a future housing application. Maybe you want to become more financially prepared before purchasing a vehicle or applying for financing.
Your goal can help you determine which problems deserve attention first.
For example, if your revolving balances are high, reducing debt may be a priority. If you discover inaccurate information, gathering evidence and addressing the reporting issue may be more appropriate.
Credit improvement should therefore be connected to your overall financial situation rather than treated as a race toward a particular score.
Do Not Forget Your Current Accounts
While addressing older credit problems, make sure you do not create new ones.
If you currently have open credit accounts, prioritize making payments on time. Consider setting reminders or automatic payments where appropriate.
Also monitor your revolving balances and avoid taking on additional debt that your budget cannot comfortably support.
Fixing an old credit-report problem while accumulating new late payments can make the overall situation harder to manage.
Build a Practical Credit Improvement Plan
A simple plan can make the process less overwhelming.
Step 1: Review
Obtain and examine your credit reports.
Step 2: Categorize
Separate potential reporting errors from legitimate negative information and current debt.
Step 3: Document
Collect statements, payment records, correspondence, and other relevant evidence.
Step 4: Address
Take appropriate action on information you reasonably believe is inaccurate and develop a repayment strategy for legitimate debt.
Step 5: Maintain
Continue making payments on time, control revolving balances, and avoid unnecessary new credit applications.
Step 6: Monitor
Review your credit information periodically and track changes.
This process is more realistic than searching for a single trick that promises an immediate score increase.
When Professional Assistance May Be Worth Considering
You may find professional guidance useful if your credit reports contain numerous accounts, several potential inaccuracies, confusing collection information, or reporting issues that you do not understand.
A credit fixing service may help organize the process and explain available options. However, consumers should still review documents carefully and understand what is being done on their behalf.
For someone searching for local assistance, comparing Philadelphia providers can help you understand differences in services, pricing, communication, and expectations.
For additional educational information, credit repair services in Philadelphia can be used as an anchor to a relevant service or resource page on your website.
Avoid the “Quick Fix” Mindset
Credit improvement is usually a process rather than a single event.
Accurate negative information may continue to appear for the period permitted by applicable reporting rules. Correcting inaccurate information can take time, and improving financial habits requires consistency.
Instead of asking, “How quickly can my score increase?” ask:
- Is my credit report accurate?
- Are my current payments on time?
- Are my balances manageable?
- Am I reducing unnecessary debt?
- Do I understand the accounts on my reports?
- Am I making informed decisions before applying for new credit?
These questions focus attention on the underlying causes of credit problems.
Take Control of the Process
Choosing professional credit assistance does not mean giving up control of your finances.
Whether you work with a credit repair consultant, use a credit fixing service, or handle the process yourself, learn what appears on your reports and understand why each step is being taken.
A thoughtful approach combines accurate information, organized documentation, responsible debt management, timely payments, and realistic expectations.
For Philadelphia consumers dealing with credit challenges, the goal should be to understand the problem first and then choose practical actions that address it. That approach can make the credit-improvement process clearer, more manageable, and more sustainable over time.

 English
 Arabic
 French
 Spanish
 Portuguese
 Deutsch
 Turkish
 Dutch
 Russian
 Romaian
 Portuguese (Brazil)
 Greek